SoLo Funds: Lend & Borrow
Solo FundsFinanceVerified
- 5.63K Reviews
- 4.6
- Downloads
- 500,000+
- Price
- Free
Screenshots
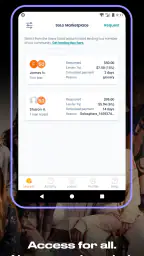
 Analysis by Appwesome
When an unexpected bill lands between paydays, the difficult part is often not the amount itself but the timing. SoLo Funds: Lend & Borrow takes a different approach from a conventional finance app by connecting people who need a short-term advance with people willing to lend. I found that this single idea changes the experience completely: instead of treating borrowing as a standard bank product, the app presents it as a community-based arrangement where users can borrow on their own terms or lend for potential returns.
That model makes SoLo Funds interesting, but it also means you need to understand what you are agreeing to before using it. This is not an ordinary budgeting tool, a savings tracker, or a replacement for a bank account. It is a finance app from Solo Funds, offered free to download, with an age rating of Everyone. Its appeal depends on whether you need a small, timely solution or whether you are looking for predictable, conventional credit.
How the lending capability changes the borrowing experience
The central capability is the two-sided marketplace. A borrower can request money for a near-term need, while a lender can browse opportunities and decide whether participating fits their own risk tolerance. That creates more choice than simply accepting whatever terms a traditional lender places in front of you, at least in principle. The important distinction is that the app is built around people helping other people, rather than only around an institution issuing credit.
In my experience, the strongest part of this concept is the control it gives the borrower over the request. The phrase “on your own terms” is not just a decorative slogan here; it describes the reason someone might open the app instead of immediately turning to a credit card or overdraft. You can approach a short-term cash problem as a specific request rather than allowing it to become a larger revolving balance.
That flexibility comes with responsibility. A request is not a magic emergency button, and access to a lending community does not remove the need to repay. I would only use the borrowing side after checking the amount against my next reliable income and leaving room for ordinary expenses. If repayment would require another advance, the app is solving the wrong problem for me.
The lending side is equally distinctive. Someone with spare funds may prefer the possibility of helping another user over leaving that money idle, but the decision is not the same as putting cash in a conventional savings product. Lending introduces uncertainty, and the attractive part of the model should never be confused with a guarantee. I would treat every opportunity as a decision requiring attention, not as an automatic way to grow money.
This is where SoLo Funds differs from many usual alternatives in personal finance. A credit card provides a reusable line, an overdraft is tied to a bank account, and a conventional personal loan generally follows a fixed institutional process. SoLo Funds sits between those familiar patterns: it focuses on individual requests and peer participation. That can feel more personal and flexible, but it may also feel less predictable than a product with standardized terms.
Other Stories to Read




What I would do before making a request
I would begin with the smallest amount that genuinely solves the immediate issue. Asking for extra room “just in case” weakens the discipline that makes short-term borrowing useful. I would then write down the repayment date alongside rent, utilities, transport, food, and any automatic payments. This simple check is more valuable than rushing through the request because it reveals whether the advance is bridging a timing gap or hiding a recurring budget shortfall.
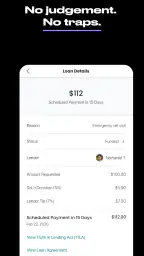
I would also read every screen carefully before confirming. Finance apps can make a process feel quick, but speed should not replace understanding. I would check the total amount involved, the expected repayment, any voluntary contribution or other displayed cost, and the consequences of missing the plan. If any wording felt unclear, I would pause rather than assume the most favorable interpretation.
For lenders, my approach would be even more conservative. I would never commit money that I might need soon, and I would avoid making a decision based only on the emotional appeal of helping someone. The potential benefit has to be weighed against the possibility of delay or loss. Spreading small amounts across separate decisions may feel safer than concentrating everything in one request, but diversification is not a promise that the overall result will be positive.
A realistic payday-gap example
Imagine that a household has enough income coming in next week but faces a necessary expense today. A short-term request could be useful if it prevents a late fee, a missed essential payment, or an interruption to something important. In that situation, the app’s value comes from timing. The borrower is not necessarily trying to finance a lifestyle; they are trying to cross a narrow gap without turning it into a long-running balance.
I would still compare the request with every available alternative first. An employer advance, a payment extension, an existing emergency fund, or help from someone I trust may be simpler and more predictable. If one of those options covers the need without creating a new repayment obligation, I would choose it. SoLo Funds becomes more compelling when those routes are unavailable, too slow, or less suitable for the situation.
The same example looks different from the lender’s perspective. A lender may like the idea of putting idle money to work while helping another person, but should ask whether the funds can remain unavailable longer than expected. The emotional reward of supporting a borrower is real, yet it should not replace basic financial caution. I would consider the lending feature only with money that is genuinely disposable.
Where the app feels practical and where it demands patience
The practical advantage is focus. Instead of opening a broad banking dashboard filled with balances and unrelated tools, you are dealing with a specific borrowing or lending decision. That narrow purpose can make the app easier to understand when the need is urgent. It also encourages me to think in terms of one request, one obligation, and one repayment plan.
The friction comes from the human nature of the marketplace. A borrower may not experience the same certainty as with an approved bank facility, because participation depends on the interaction between borrowers and lenders. A lender, meanwhile, has to accept that a promising opportunity is not equivalent to a guaranteed outcome. This uncertainty is not a minor detail; it is the main trade-off behind the app’s distinctive approach.
I would also avoid confusing a free download with a cost-free financial decision. The app itself is listed as free, but borrowing and lending can still involve terms, contributions, or consequences that matter. Before proceeding, I would inspect the current in-app details rather than relying on a general impression from the app’s price label. That is especially important if you are comparing it with a bank product whose fees are presented in a more familiar format.
Another limitation is behavioral. The convenience of requesting money can make repeated borrowing feel normal. If the same type of expense appears every week, a series of short-term solutions may become more expensive and stressful than addressing the underlying budget. I see the app as a bridge for an occasional mismatch between income and expenses, not as a permanent extension of income.
Questions I would settle before using it
Is it suitable for a first-time borrower? It can be, but only if that person is willing to read the terms and create a repayment plan before requesting funds. I would not recommend opening it while panicking and accepting the first available option. A first-time user should understand the difference between receiving money quickly and being able to repay it comfortably.
Can it replace a traditional bank loan? Not in every situation. A larger, planned expense may be better served by a conventional product with clearly scheduled payments and familiar underwriting. SoLo Funds makes more sense when the need is short-term and specific, while a bank or credit union may be preferable when you need a structured loan with longer repayment planning.
Should someone use the lending side for dependable income? I would say no. The possibility of earning a return may be appealing, but lending is not the same as receiving interest from a guaranteed deposit. Anyone considering it should be comfortable with uncertainty and should keep essential money elsewhere. The feature is better viewed as an optional allocation of spare funds than as a replacement for wages or savings.
What if repayment becomes difficult? I would contact the relevant support channel inside the app as soon as the problem appears and review the applicable terms. Waiting until the due point can reduce your options. More importantly, I would treat difficulty repaying as a signal to stop taking new advances until the existing obligation is resolved.
Is it appropriate for someone who needs money regularly? Usually, that is where I would hesitate. Regular need suggests an income, expense, or debt issue that a marketplace advance cannot fix. A budget review, benefits check, debt counseling service, or conversation with a financial institution may provide a more durable answer. The app is strongest when the problem is temporary rather than structural.
Who gets the most value from the app
The best fit is someone who has a clear, near-term repayment source and wants an alternative to a credit card or overdraft. That person should be able to distinguish an emergency from an impulse, compare options calmly, and repay without sacrificing essentials. For them, the community-based structure may offer a useful middle ground between asking a friend directly and applying for a conventional loan.
It may also suit a cautious lender who understands that helping someone and seeking a possible return both involve risk. Such a user needs patience, spare funds, and a willingness to review each decision individually. I would not recommend the lending side to anyone who needs certainty, immediate access to every dollar, or a guaranteed result.
People who should probably skip it include anyone already juggling several repayments, anyone unsure when their next income will arrive, and anyone looking for a simple savings account. It is also not my first choice for a planned purchase that can wait. Saving first is slower, but it avoids turning a want into a debt obligation.
My overall view after weighing the trade-offs
SoLo Funds is most convincing when viewed through its core capability rather than as a general-purpose money app. Its peer-to-peer borrowing and lending model gives short-term finance a more human and flexible shape, and that can be genuinely useful during a narrow cash-flow gap. The same design also makes it less suitable for users who want institutional predictability or a guaranteed financial outcome.
The app has built a substantial audience, with an average rating of 4.6 from around 25 thousand ratings and more than 500 thousand installs. Those figures suggest that the idea resonates with many users, although popularity does not remove the need to judge each request or lending decision carefully. I also noted that it is marked for Everyone, runs on Android 8.0 or later, and is currently at version 2.19.0, details worth checking against your device before installing.
My recommendation is conditional but positive: use it when the amount is limited, the repayment source is dependable, and you have compared less complicated alternatives. Do not use it to cover a recurring deficit, and do not lend money you cannot afford to leave uncertain. The real strength of SoLo Funds is controlled flexibility, not effortless access to cash. If you approach it with that mindset, its unusual model can be useful; if you need certainty, a traditional financial provider is likely the better choice.
Highlights
- Borrowers can request small loans without traditional credit checks.
- The app supports peer-to-peer lending within a community-driven platform.
- Users can build a reputation through repayment history and activity.
- Mobile access makes managing requests and repayments convenient.
- Lenders can choose which borrower requests they want to support.
Limitations
- Loan availability may depend on community funding and user demand.
- Borrowers may face platform or service fees on certain transactions.
- Late repayments can negatively affect a user’s standing in the community.
- Peer-to-peer loans may not offer the same protections as bank products.
- Eligibility
- limits
- and features can vary by location and account history.
Frequently Asked Questions
01What is SoLo Funds: Lend & Borrow, and how does it work?
SoLo Funds is a community-based financial platform designed to let members request small, short-term advances from other users instead of using a traditional payday lender. A borrower creates a request, explains the amount and repayment date, and lenders can choose whether to fund it. After repayment, borrowers may leave an optional tip and contribution, depending on the app’s current terms and policies.
02Is SoLo Funds a bank or a traditional loan service?
No. SoLo Funds is not a conventional bank, credit union, or standard personal-loan provider. It operates as a technology platform that connects people seeking short-term financial assistance with members willing to provide funds. Availability, eligibility, fees, repayment rules, and account features can change, so users should carefully review the latest disclosures and terms before requesting or providing money.
03Can anyone borrow or lend money through SoLo Funds?
Not necessarily. Users generally need to meet the platform’s eligibility, identity-verification, location, and account requirements before accessing borrowing or lending features. Approval and available amounts may also depend on account history, platform rules, and other factors. Before downloading or depositing funds, check whether the service is currently available in your state or region and confirm the requirements shown in the app.
04How much does SoLo Funds cost, and are there fees or tips?
The cost can vary according to the type of transaction and the platform’s current policies. Borrowers may be asked to select a voluntary tip or contribution, while additional charges or consequences may apply in certain situations, such as late repayment or optional features. Because pricing and disclosures can change, read the complete fee information in the app before accepting an advance or funding another user.
05What happens if I cannot repay a SoLo Funds advance on time?
Missing a repayment date can affect your account standing and may limit your ability to use the service in the future. Depending on the applicable terms, late payments may also involve additional consequences, collection activity, or other costs. If repayment problems arise, review the app’s support options immediately and contact SoLo Funds rather than assuming an extension is automatic or guaranteed.


